
By Angelo Meda, Head of Equities at Banor
For Big Tech, this year has definitely been more trick than treat.
Halloween may be over, but in financial markets the last two weeks have felt very much like a night of witches and ghosts.
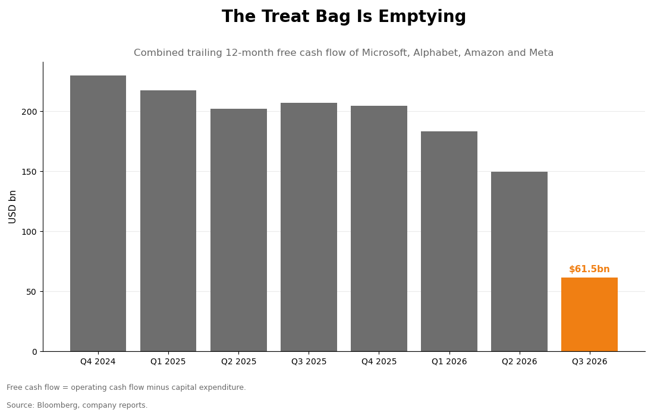
Alphabet wiped out nearly $500 billion in market capitalisation in a single trading session, the worst day in its history. Amazon disappointed with a quarter that fell short of expectations and a record cash burn. Intel did not even need a costume: the day after reporting results, its stock dropped almost 30%, its worst day since 1974, chilling investors more effectively than any haunted house.
The real ghost of the season emerged with Oracle’s investment plan, which places the peak of spending in 2028. Meanwhile, for the first time in several quarters, hyperscalers have not significantly raised their capex plans, something that had become a routine occurrence until last quarter. Even so, discussion remains focused more on supply bottlenecks than weakening demand, with chips, energy, and data centres simply not arriving fast enough.
Stock markets remain highly emotional. They look at the numbers, but often react more to a CFO’s tone, a misplaced word during an earnings call, or guidance delivered with slightly less enthusiasm. Investors read the financial statements, but they also seem to check their horoscope, meaning that euphoria and panic frequently arrive before the Excel spreadsheet does.
Elections, another topic we will be dealing with frequently, have remained little more than footnotes for global indices, but not for local assets. In Brazil, Lula’s victory, which caught markets by surprise, cost the Bovespa 18% in one week, while the Brazilian real fell 9% against the dollar. In Israel, an uncertain election result also weighed on equities and the shekel. As with any respectable Halloween, there was also a theft: $6.3 billion stolen from Binance, the largest cryptocurrency heist in history. The monsters have not disappeared, they have simply changed masks and addresses.
Central banks remain on hold, but vigilant. At the Federal Reserve, two members voted in favour of raising interest rates. The European Central Bank also discussed the possibility of further hikes. Meanwhile, Christine Lagarde announced that she will step down as ECB President in February, ahead of schedule. Successful investing today requires careful stock selection, discipline, and a flashlight capable of distinguishing a genuine slowdown from mere noise in the corridor.
The pumpkins are going back into storage and the first Christmas lights are coming on. Post the November midterm elections and Nvidia’s earnings on 17 November, market rumours suggest that the IPO of Anthropic could take place in the second half of the month. It would be the season’s biggest package, arriving even before the Christmas tree. Will it be the sweet treat that kicks off the Santa Claus rally, or the final trick before central banks make their next move?
Overall, the market resembles a haunted house where doors slam in both directions. On one hand, demand for artificial intelligence remains strong, cloud computing continues to expand rapidly, the year-end calendar promises significant corporate events, and the recent market pullback has made valuations somewhat less stretched.
On the other hand, concerns remain about the return on investment spending, shrinking cash reserves, persistent inflation, elevated real interest rates, and central banks that have not ruled out further increases. With forces so evenly balanced, betting aggressively on either a bull or bear market is like trying to guess who is hiding under the sheet.
That is why it is essential to focus on strong companies with robust balance sheets, visible cash flows, and defensible competitive advantages. These are businesses capable of growing if the party continues, but also of protecting portfolios if conditions change. The right Halloween bag is not the fullest one, but the one that does not tear when somebody pulls on it.
So, trick or treat? For now, the answer remains behind the door, and whoever is knocking has not yet removed their mask.
This communication is issued by Banor Capital Limited which is authorised and regulated by the Financial Conduct Authority (FRN: 523080). For Professional Clients and Eligible Counterparties only. Not for Retail clients. The content is for information purposes only and does not constitute investment advice, a recommendation, or an offer/solicitation to buy or sell any investment. Views are those of the speaker and may change. Any views expressed regarding future market conditions, sector performance, or investment returns are forward-looking statements and may not materialise. Actual outcomes may differ materially. Forecasts are not a reliable indicator of future performance. This communication is not directed to any person in any jurisdiction where doing so would be unlawful; distribution may be restricted.
Angelo Meda is Head of Equities at Banor SIM S.p.A. and provides research and advisory input to Banor Capital Ltd pursuant to an advisory agreement.
This article is an English translation of an article originally prepared and published by Banor SIM.